Publicly traded oil and gas companies represent only 2% of roughly 12,000 U.S. producers, yet they accounted for 68% of crude oil and natural gas production in the Lower 48 states in 2025. Their dominance is largely attributed to high-quality drilling locations, advanced technology, economies of scale, and lower production breakeven prices.
The largest operators control a significant share of production. The 12 companies with the most wells represent less than 1% of all producers, while 64% of operators have 10 or fewer wells and are mostly small stripper-well producers.
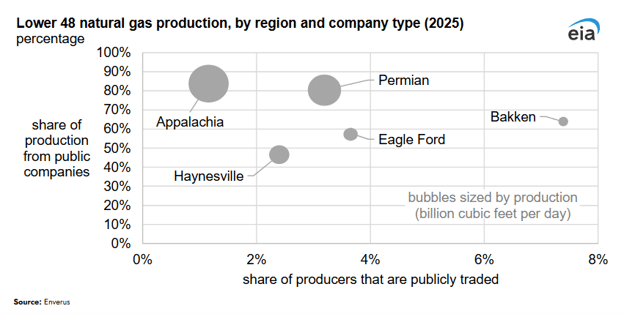

Public companies dominate major producing regions such as the Permian and Appalachia, where they produce roughly four to five times as much as private companies despite representing only a small percentage of operators. The Haynesville region is the main exception, with private companies producing 55% of the region’s oil and gas. Production there is concentrated among a handful of large private operators, with the top five private natural-gas producers alone accounting for 38% of regional gas output.