
The U.S. Census Bureau’s September 2026 Construction Spending Report shows a slowdown in overall construction activity, with total construction spending down 1.9% from August to an annualized rate of about $2.186 trillion, a 2.7% decrease from September 2025. Private construction spending fell 2.4%, driven mainly by a 5.5% drop in residential construction. Public construction spending remained relatively stable, decreasing just 0.1%, providing some support to the overall market.
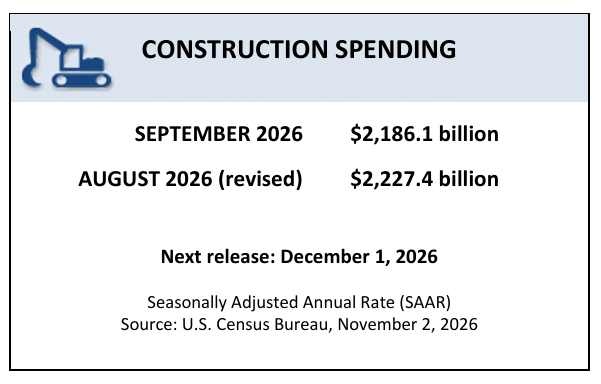
The report reflects an uneven construction market, characterized by weakening residential activity and reduced investment in manufacturing, offset by growth in selected commercial and infrastructure sectors. Year-to-date construction spending declined about 2.9% from the same period in 2025, with private construction weakening while public investment increased slightly. These trends suggest that construction investment is becoming increasingly concentrated in specific nonresidential and infrastructure markets rather than reflecting broad-based industry growth.